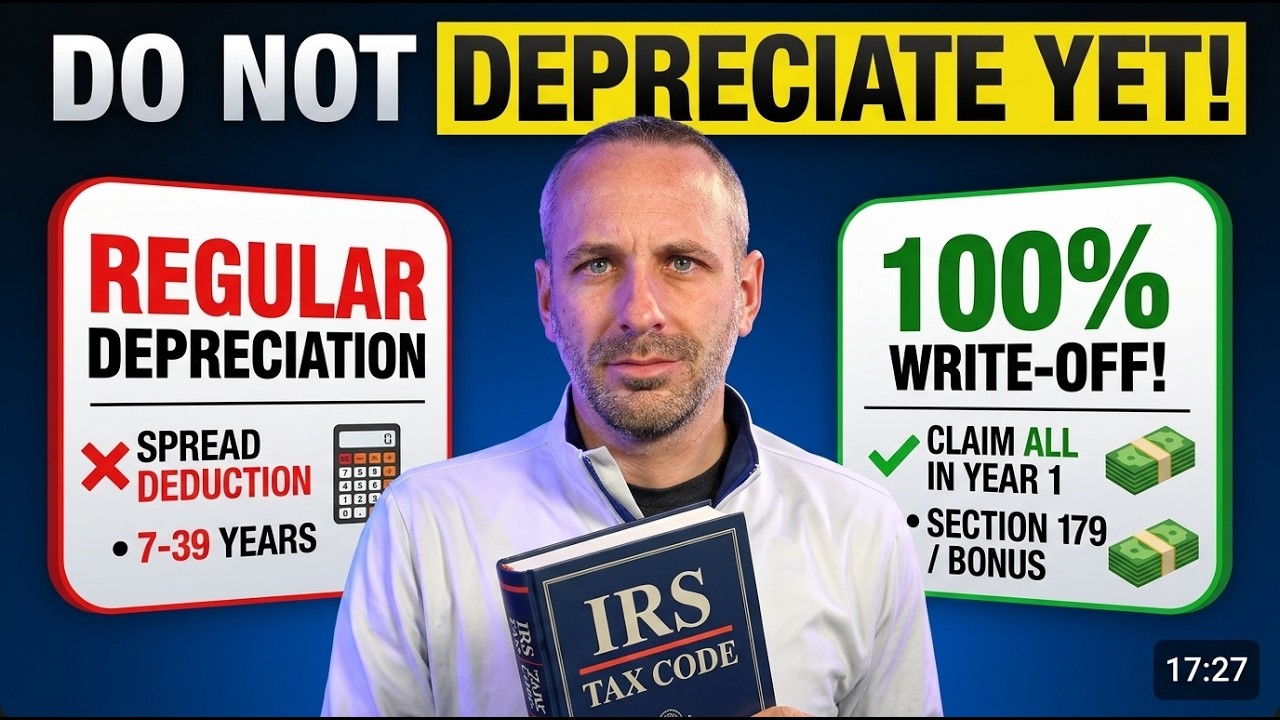
Understanding the business equipment tax write-off rules can make a significant difference in how much you pay in taxes. Depending on what you purchase, when you start using it, and which deduction method you choose, you may be able to deduct the full cost in the first year.
However, taking the largest deduction immediately isn’t always the best decision.
In this guide, we’ll break down how business depreciation works, the differences between Section 179 and bonus depreciation, and how a simple capitalization policy can help you maximize eligible deductions while keeping your bookkeeping organized.
TL;DR: Business Equipment Tax Write-Offs in 2026
-
100% bonus depreciation: Eligible business equipment acquired and placed in service after January 19, 2025, can qualify for a full first-year deduction.
-
Section 179 deduction: Allows businesses to immediately deduct qualifying purchases, subject to annual limits and taxable business income requirements.
-
Regular depreciation: Spreads equipment deductions over several years rather than claiming the entire amount immediately.
-
$2,500 expense rule: The IRS de minimis safe harbor generally allows businesses without applicable financial statements to expense qualifying purchases of $2,500 or less per invoice or item.
-
Business-use requirements: You can generally deduct only the business portion of purchases used for both personal and business purposes.
-
Year-end deadline: To claim depreciation for 2026, qualifying equipment generally must be placed in service by December 31, 2026, for calendar-year businesses.
The right strategy depends on your income, the equipment you’re purchasing, and whether taking the deduction now or in future years provides greater tax savings.
How Does a Business Equipment Tax Write-Off Work?
When you purchase equipment for your business, the IRS generally treats items expected to last longer than one year as capital assets.
This means you typically don’t deduct the entire purchase as an ordinary business expense. Instead, you recover its cost through a process called depreciation.
Depreciation allows you to deduct the cost of qualifying business assets over a period established by the IRS.
For example, if you purchase a $30,000 piece of equipment, you may need to spread that deduction over several years. However, certain tax provisions allow eligible businesses to accelerate those deductions and potentially claim the entire cost in the first year.
According to the IRS depreciation guidelines, the available deduction depends on the type of property, when it is placed in service, and the depreciation rules that apply.
What Business Equipment Can You Write Off?
Common examples of qualifying business assets include:
-
Computers, laptops, and office technology
-
Machinery and manufacturing equipment
-
Business vehicles and trucks
-
Office furniture and fixtures
-
Tools and specialized business equipment
-
Certain improvements to commercial property
The IRS assigns different depreciation periods based on the type of asset.
For example, computers and business vehicles are commonly classified as five-year property, while office furniture is generally seven-year property. Commercial buildings typically have a 39-year recovery period.
These classifications matter because many assets with recovery periods of 20 years or less can qualify for accelerated depreciation.
Section 179 vs. Bonus Depreciation: What’s the Difference?
There are three primary methods businesses can use to deduct the cost of qualifying equipment.
Understanding the differences helps you determine which approach fits your business and tax situation.
1. Regular Depreciation: Spread Your Deduction Over Time
Regular depreciation allows you to deduct an asset’s cost over its assigned recovery period.
For example, if you purchase $60,000 of seven-year equipment, you would deduct its cost over multiple tax years using the applicable IRS depreciation schedule.
This approach can be useful when your business expects higher income in future years and you want deductions available during those periods.
Although regular depreciation generally provides a smaller deduction upfront, it can help distribute tax benefits across several years.
2. 100% Bonus Depreciation: Deduct Qualifying Equipment in Year One
Under current federal law, businesses can claim 100% bonus depreciation on qualifying property acquired and placed in service after January 19, 2025.
This means eligible purchases made in 2026 may qualify for a full deduction in the first year.
Qualifying assets can include machinery, computers, certain vehicles, office furniture, and eligible property improvements. Both new and certain used assets may qualify.
One important advantage is that bonus depreciation can create a business tax loss.
For example, suppose your business has $100,000 in profit and purchases $150,000 in qualifying equipment.
If the entire purchase qualifies for 100% bonus depreciation, the deduction could reduce your business’s taxable result to a $50,000 loss.
Whether that loss reduces other taxable income depends on additional rules, including business-loss, basis, at-risk, and passive-activity limitations.
The IRS provides details on 100% bonus depreciation eligibility and requirements.
3. Section 179: Deduct Equipment Without Creating a Business Loss
Section 179 also allows businesses to immediately deduct the cost of qualifying equipment, but there are important differences.
Unlike bonus depreciation, Section 179 is generally limited by taxable income from the active conduct of a trade or business.
For tax years beginning in 2026, the IRS sets the maximum Section 179 deduction at $2,560,000. The deduction begins phasing out when total qualifying property placed in service exceeds $4,090,000.
These are official federal limits, and additional restrictions can apply to specific types of assets, including vehicles.
For example, if your business has $100,000 in qualifying taxable business income and purchases $150,000 of eligible equipment, the income limitation generally prevents you from using Section 179 alone to create a $50,000 loss.
The unused amount may be carried forward, subject to applicable rules.
Section 179 also allows you to choose which qualifying assets receive the deduction, giving you more control over your tax planning.
You can review these rules in IRS Publication 946: How to Depreciate Property.
Comparing the Three Depreciation Methods
| Method | When you deduct the cost | Key consideration |
|---|---|---|
| Regular depreciation | Over multiple years | Preserves deductions for future years |
| 100% bonus depreciation | Generally in the first year for qualifying assets | Can create a business tax loss |
| Section 179 | Immediately, within applicable limits | Limited by qualifying business income |
You can also use Section 179 and bonus depreciation together when the purchases and applicable rules allow it.
How Much Can You Save With a Business Equipment Tax Write-Off?
Consider a business purchasing $60,000 in qualifying seven-year equipment.
For this simplified example, assume the business has a 30% combined marginal tax rate, the equipment is used entirely for business, and the applicable deductions can be fully utilized.
Example: $60,000 equipment purchase
Regular depreciation
$2,600
Approximate first-year tax savings
100% accelerated deduction
$18,000
Potential first-year tax savings
Simplified comparison assuming a 30% marginal tax rate and full deductibility.

The accelerated deduction provides approximately $15,400 more in first-year tax savings in this simplified scenario. It generally changes the timing of deductions rather than increasing the original equipment cost that can be recovered.
Under regular depreciation, the first-year deduction would be approximately $8,500 using the standard seven-year MACRS schedule and assuming the half-year convention applies.
At a 30% tax rate, this produces approximately $2,600 in first-year tax savings.
With 100% bonus depreciation, the business could deduct the full $60,000 in year one. At the same assumed tax rate, that would produce approximately $18,000 in tax savings.
The difference is substantial, but this does not automatically mean accelerated depreciation is better.
Your actual savings depend on your tax bracket, other income and deductions, eligibility restrictions, state tax treatment, and how the equipment is used. Future asset sales can also create taxable depreciation recapture.
When Does It Make Sense to Write Off Equipment Immediately?
When Your Business Has a Profitable Year
If your business is generating substantial income, claiming a larger deduction this year may help reduce your current tax liability.
For example, if you expect $200,000 in taxable business income and need to purchase $50,000 in equipment, accelerating the deduction could lower the amount of income subject to federal income tax.
The benefit depends on your marginal tax rate and whether the deduction is fully allowable.
When You Need Equipment to Grow Your Business
Tax deductions work best when they support purchases your business already needs.
Maybe you need to replace outdated computers, purchase manufacturing equipment, or upgrade a vehicle used for operations.
If these purchases are necessary, understanding available equipment tax deductions can help you make the investment more tax-efficient.
However, spending money solely to obtain a deduction rarely makes financial sense.
If you spend $1 to save 30 cents in taxes, you’ve still spent 70 cents.
When You Want to Offset Other Taxable Income
Bonus depreciation may be useful when a business wants to create a tax loss that could offset other qualifying income.
This can be especially relevant for business owners with multiple income sources.
However, not every business loss can be used immediately against other income. Your entity structure and applicable loss limitations determine how much benefit is available.
When Is Taking the Full Deduction a Bad Idea?
When You Expect Higher Income Next Year
Suppose your business has a relatively low-income year in 2026 but expects significantly higher earnings in 2027.
Taking a large deduction in the lower-income year could provide less tax savings than deductions used in a future year with a higher marginal tax rate.
For example, a $10,000 deduction used at a 12% marginal tax rate represents approximately $1,200 in tax savings.
The same deduction used at a 32% marginal tax rate represents approximately $3,200 in savings.
These simplified calculations illustrate why the timing of deductions matters. Actual outcomes depend on the tax rules and income available in each year.
When You Plan to Sell the Equipment Soon
If you deduct the entire cost of equipment and later sell it, you may owe taxes on some or all of the sale proceeds.
This is known as depreciation recapture.
For example, suppose you purchase a $4,000 computer, deduct its entire cost, and later sell it for $1,000.
Assuming no other basis adjustments, your adjusted tax basis would be zero, and the $1,000 sale would generally result in taxable gain, ordinarily treated as depreciation recapture.
This doesn’t necessarily make accelerated depreciation a bad strategy. It means you need to consider the tax consequences beyond the initial purchase.
When Your State Doesn’t Follow Federal Depreciation Rules
Some states do not fully follow federal bonus depreciation rules.
Your business may qualify for a full federal deduction while being required to spread the deduction over several years for state income tax purposes.
Review both federal and state treatment before estimating your total tax savings.
The $2,500 Business Expense Deduction: Why You Need a Capitalization Policy
One commonly overlooked tax planning opportunity is the IRS de minimis safe harbor, often implemented through a business capitalization policy.
For businesses without applicable financial statements, this election generally allows qualifying purchases costing $2,500 or less per invoice or item to be expensed immediately rather than capitalized and depreciated.
For example, suppose your business purchases:
-
Two desks costing $2,200 each
-
Three laptops costing $1,500 each
-
Office tools totaling $3,100, with each individual item below $2,500
If the purchases meet the safe harbor requirements, the business may be able to expense the qualifying items immediately without creating individual depreciation schedules for them.
This simplifies bookkeeping and reduces the administrative work associated with tracking multiple small assets.
How to Establish a Capitalization Policy
A capitalization policy explains how your business treats purchases that fall below a designated expense threshold.
A practical approach is to establish a consistent accounting policy that expenses qualifying purchases at or below $2,500.
The IRS requires taxpayers without applicable financial statements to follow a consistent accounting procedure or policy that exists at the beginning of the tax year. A written policy is recommended for documentation, although the IRS does not require it to be written for these taxpayers.
A written policy adopted before January 1, 2027, can help establish consistent procedures for the upcoming calendar tax year.
To use the safe harbor, you must also make the required annual election by attaching a statement to your timely filed original federal income tax return, including extensions.
The IRS tangible property regulations and de minimis safe harbor guidance explain the threshold, accounting requirements, and election process.
Watch Out for the Invoice Mistake
Suppose you purchase two office desks for $2,200 each.
Your total invoice is $4,400, which exceeds the $2,500 threshold.
However, if the invoice clearly itemizes the two desks separately and each qualifies under the applicable rules, you may still be able to expense both items under the safe harbor.
This is why detailed invoices matter.
A single transaction amount in your bookkeeping software doesn’t always tell you whether the individual items qualify for immediate expensing.
Important IRS Requirements for Equipment Tax Deductions
Claiming a business equipment tax write-off requires more than purchasing an eligible asset.
You must also meet the applicable IRS requirements and maintain documentation supporting the deduction.
1. Equipment Must Be Placed in Service
The date you purchase equipment isn’t necessarily the date you can begin depreciating it.
The IRS generally considers equipment placed in service when it is ready and available for its intended business use.
For example, suppose you purchase an $8,000 computer on December 15, 2026, but it requires additional setup and isn’t ready for use until January 10, 2027.
Even though you purchased it in December, the equipment generally wouldn’t qualify for a 2026 depreciation deduction because it wasn’t placed in service until 2027.
This distinction is especially important when planning equipment purchases near year-end.
2. You Can Only Deduct the Business-Use Portion
If equipment is used for both business and personal purposes, you generally cannot deduct the entire cost.
Suppose you purchase a $30,000 SUV and use it 70% for business.
The business-use portion would be:
$30,000 × 70% = $21,000
That $21,000 would be the portion potentially eligible for business depreciation, before applying vehicle-specific limits and other requirements.
For certain vehicles and other listed property, business use must exceed 50% to qualify for accelerated deductions. Special vehicle depreciation caps may also apply.
You can review these limitations in IRS Publication 463: Travel, Gift, and Car Expenses.
3. Maintain Proper Records
For every significant business asset, keep records of:
-
Purchase price and date
-
Date placed in service
-
Equipment description
-
Business-use percentage
-
Receipts and itemized invoices
-
Depreciation method used
-
Depreciation previously claimed
These records help support your deductions and establish the asset’s adjusted tax basis when you eventually sell or dispose of it.
Hidden Costs and Responsibilities of Equipment Write-Offs
Financing Equipment Doesn’t Eliminate the Debt
A business may qualify to depreciate the full eligible cost of equipment purchased with financing, even if it only makes a small down payment.
However, the deduction doesn’t eliminate the loan or the obligation to make future payments.
Before making a financed purchase, evaluate whether your business can comfortably afford the payments regardless of the tax savings.
Depreciation Recapture Can Create Future Taxes
Accelerated depreciation reduces your equipment’s adjusted tax basis more quickly.
When the equipment is sold, a lower adjusted basis can lead to a larger taxable gain.
That future tax obligation should be part of your original purchasing decision.
Administrative Work Can Add Up
Equipment depreciation requires accurate asset tracking, bookkeeping, and potentially additional tax preparation work.
A properly implemented capitalization policy can reduce this workload for qualifying smaller purchases.
Larger assets still require appropriate classification, documentation, and depreciation reporting.
Business Equipment Tax Write-Off Checklist for 2026
Before making a major equipment purchase or choosing a depreciation method, consider these questions:
Reviewing these questions before year-end can help you identify opportunities and prevent mistakes that are difficult to correct after the tax year closes.
Make the Most of Your Business Equipment Tax Write-Off
A business equipment tax write-off can help reduce your tax bill, but the best deduction isn’t necessarily the largest one available today.
Bonus depreciation and Section 179 can allow qualifying purchases to be deducted immediately, while regular depreciation may provide greater value when your income is expected to increase in future years.
A consistent capitalization policy can also make it easier to expense qualifying smaller purchases without unnecessary asset tracking.
The important thing is to plan ahead. Understand what qualifies, evaluate the timing of your deductions, and make purchasing decisions that support your business.
Before following advice to purchase a truck or expensive piece of equipment simply for a tax write-off, run the numbers and determine whether the investment makes financial sense.
Find More Tax Savings Opportunities in Your Business
Are you taking advantage of all the tax deductions available to your business?
Our free Tax Savings Scorecard helps you identify potential tax-saving opportunities and areas where your current tax strategy may be falling short.
Answer a few questions about your business to see which strategies may deserve a closer look.
Take the Free Tax Savings ScorecardIf you want help implementing strategies such as depreciation planning, Section 179, and capitalization policies, explore TaxElm’s tax planning tools and services.
Frequently Asked Questions About Business Equipment Tax Write-Offs
1. Can I write off 100% of business equipment in 2026?
Yes, qualifying equipment may be eligible for a 100% business equipment tax write-off under bonus depreciation or Section 179. The amount you can deduct depends on the type of equipment, business use, placed-in-service date, and applicable tax limitations.
2. What is the difference between Section 179 and bonus depreciation?
Both methods allow eligible businesses to accelerate equipment deductions. However, Section 179 is subject to annual deduction limits and taxable business income requirements, while bonus depreciation can create a business loss, subject to other applicable limitations.
3. Can I write off a business vehicle in 2026?
Yes, business vehicles may qualify for depreciation deductions, including Section 179 or bonus depreciation. The amount depends on the vehicle type, business-use percentage, and applicable IRS limits, including special restrictions for passenger vehicles and heavy SUVs.
4. What is the $2,500 business expense rule?
The IRS de minimis safe harbor generally allows businesses without applicable financial statements to expense qualifying purchases costing $2,500 or less per invoice or item. To use this treatment, businesses must follow the applicable accounting procedures and make the required annual election on their tax return.
5. Can I deduct equipment purchased with a business loan?
Yes, qualifying equipment purchased with financing may be eligible for depreciation based on its full eligible cost, even if you haven’t paid the entire loan balance. The equipment must meet the applicable depreciation requirements, and financing does not eliminate your responsibility to repay the debt.
6. Do I have to purchase business equipment before December 31?
For a calendar-year business seeking a 2026 depreciation deduction, the equipment generally must be placed in service by December 31, 2026. Purchasing equipment before the deadline isn’t enough if it isn’t ready and available for its intended business use until the following year.
7. Is bonus depreciation better than regular depreciation?
Bonus depreciation may provide greater immediate tax savings because qualifying equipment can be deducted in the first year. However, regular depreciation may be more beneficial when you expect higher taxable income in future years or want to avoid accelerating deductions into a lower tax bracket.
8. Can I write off computers and laptops for my business?
Yes, computers and laptops used for business generally qualify for deductions. Depending on their cost and your accounting procedures, they may qualify for immediate expensing under the de minimis safe harbor, Section 179, or bonus depreciation. Otherwise, they may be deducted through regular depreciation.
9. What happens if I sell equipment after taking bonus depreciation?
Selling equipment after claiming bonus depreciation may result in taxable gain, including depreciation recapture. Because the original deduction reduces your adjusted tax basis, selling the asset later can create taxable income even when you sell it for less than its original purchase price.
10. Should every small business have a capitalization policy?
A consistent capitalization policy is a useful practice for businesses that regularly purchase equipment, technology, and other assets. It helps establish when qualifying smaller purchases are expensed immediately and when larger purchases need to be capitalized. While written policies are not required for every taxpayer, documenting your procedures helps support consistent bookkeeping and tax reporting.